Restoration Company Business Plan: Key Components & How to Write One
Restoration SEO
August 10, 2026
For your restoration company business plan to work, you’ll need to develop a clear roadmap on how your business will attract customers, manage daily operations, generate revenue, handle challenges, and grow sustainably before you start responding to emergency calls.
Although many restoration businesses draft a business plan only to attract investors, its real superpower is that it helps you make better, informed decisions before mistakes become too costly to manage.
Developing a business plan from scratch can give you an unfair advantage, as experts say that most restoration companies operate without one.
So, how do you build one that works effectively?
Today, we’ll go through each section of a complete restoration company business plan, explain what to include, and give you a blueprint on how to keep leveraging your business plan in the long run.
Let’s build a restoration company business plan that’s realistic, convincing, and built for long-term success.
Key Components of a Restoration Company Business Plan
Restoration companies usually write a business plan when they want a bank loan or an investment. So, aside from you, the business owner, two other people will also check it: the banker who’ll approve your loan, and the investor who sees potential in your business.
The banker will check if you’ve done your homework, and the investor will evaluate your financials and market analytics. To both of them, your business plan is simply a piece of paper that validates your business potential.
In truth, it’s so much more than that. Smart business owners use this playbook to ensure that their business growth is planned, rather than just a happy accident.
Once you start writing your restoration company business plan, you’ll need to answer these practical questions:
- What types of restoration jobs will you take?
- Who are your ideal customers?
- What will your day-to-day operations look like?
- How much equipment and manpower can you realistically afford?
- How do you plan to surpass your competitors?
- How will you consistently win new work?
- How do you plan to grow your business sustainably?
Working through these questions on paper will help you identify potential challenges before they become costly mistakes.
A complete business plan usually has 10 sections. Let’s explore what each section contains and how you can craft a solid business plan for your restoration company from scratch.
Section 1: Executive Summary (Write It Last)
The Executive Summary is a one- or two-page snapshot that contains all the key details about your business strategy. In other words, it’s a compact version of your entire business plan.
It’s also the most important one since busy readers use this quick overview to decide whether they’ll read the whole document. As a result, your executive summary should contain a fluff-free description of your company, your audience, your target market, your competitive edge, and the numbers that matter.
That’s why we recommend writing this section last and polishing it rigorously. Once you develop a clear picture of the roadmap ahead, you’ll be able to summarize it much more efficiently.
For your restoration business, these are the sections worth highlighting in this summary:
- Your Company Overview (Name, niche, service area)
- Market Analysis with Stats (Target market, local demand, growth opportunity)
- Your Competitive Edge (Competitors, UVP, growth strategy)
- Your Financials (Startup cost, revenue target, projections)
Don’t try to explain here; you’ll get the opportunity later. Try to give the reader enough detail to communicate that you’ve built a realistic plan.
Also, you need to make it engaging so the reader keeps on reading. That’s a hard task to complete, and that’s another reason why we suggested you tackle this at the very last.
Here’s how to ensure your executive summary stands out: Hand it to someone who has no idea about your business. If they can explain your core ideas, your executive summary is heading in the right direction.
Section 2: Company Description (Set Your Business Direction)
The primary goal of this section is to set your business direction, and that’s what separates this from the “About Us” page on your website.
Aside from your basic business details like name, mission, vision, or location, this section also decides where the following sections are headed. For instance, your legal structure, licensing, service areas, certifications, and most importantly, your niche.
In other words, your company description will inform readers about who you are, what your business does, and where you plan to take it.
- Start With The Basics (Company Overview)
Clearly state your business name, launch date, legal entity, ownership/licensing info, business location, industry credentials, and service locations.
The legal entity is especially important. It covers the legal ground for your restoration company. Your ideal choice will depend on the level of liability protection you want.
For instance, if you don’t need any liability protection, you can choose between a sole proprietorship (independent business) and a partnership.
Limited Liability Companies (LLC) offer personal liability protection for the owners and pass-through taxation. Corporation models (S-Corp or C-Corp) offer the strongest liability protection, but are complicated to set up and maintain.
Next comes your mission and vision. Mission defines your core purpose today: what problems are you currently solving and how, whereas vision portrays the long-term impact of your company: where you are headed, and when you plan to reach there.
Lastly, you’ll need to define the areas you plan to serve. Don’t try to name all the neighborhoods you can remember. The gold standard is a 60-min drive radius centering your warehouse/physical location.
- Choose Your Niche
Next, choose your niche. This includes the services you plan to offer and your target audience (the customer you want to serve).
Here are the primary niches you can choose from:
- General Cleaning Services (Carpet Cleaning, HVAC/Air Duct Cleaning, Tile/Grout Restoration)
- Water Damage Restoration (Standing Water Extraction, Fixing Burst Pipe/Leaks)
- Fire & Smoke Damage Restoration (Corrosive Residue Mitigation, Deodorizing Properties)
- Mold Remediation (Containing, Removing, and Preventing Mold Growth)
- Storm Damage Restoration (Emergency Tarping/Boarding, Wind/Hail Damage Repair)
- Biohazard/Sewage Cleanup (Waste Disposal, Pathogen/Virus Decontamination, Trauma/Lab Cleanup)
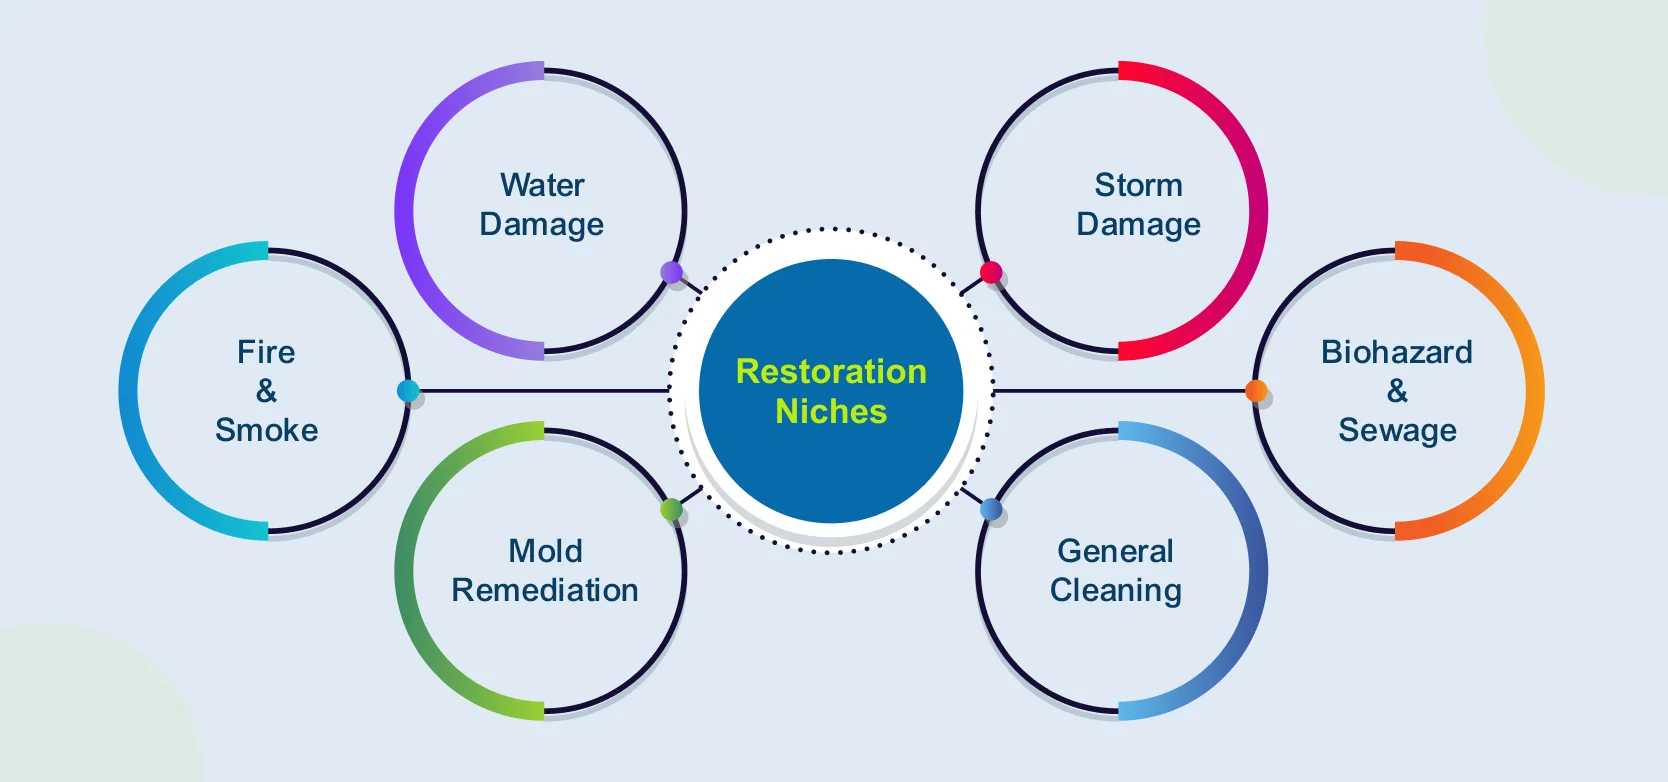
Each niche requires different expertise, equipment, and strategy.
For instance, water damage restoration is the most common and has lower equipment costs; mold remediation faces heavier regulations, and reconstruction has longer cash cycles.
Each of them needs different equipment, strategy, expertise, and finance options. So, this section should focus on both how you plan to start today and how you want to grow your restoration business in the future.
- Choose Your Business Model
Next comes choosing your business model. Here, you’ll decide the growth strategy for your finances and services. For instance,
- Will you focus on residential or commercial projects, or both?
- Will your cash inflow prioritize insurance claims or cash payments?
- Will you depend on the franchise model, or grow as an independent business?
- Will you start as a niche business or provide complete restoration services from the get-go?
There is no universal “best” business model you can copy and paste. Your experience, local market, long-term goals, and available capital will help you choose your ideal business model.
To give you an idea, if you choose the franchise route, you’ll get quick access to structured corporate systems and built-in insurance networks, but you’ll need to pay regular fees and strictly follow their rules.
On the other hand, if you choose to be an independent business, you can keep 100% of your profits, but you’ll need to build your own system and network from scratch.
The most common mistake we see business owners make at this stage is that they try to position themself as a full-service restoration company from day one. As a result, they quickly become exhausted, and managing day-to-day operations turns into a nightmare.
We suggest you start with a narrower focus (for example, mold remediation). This’ll allow you to build expertise and reputation over time. Once you’re confident and prepared enough, you can take your business to new, broader directions.
- Explain Your Competitive Edge
Your next job is to highlight what separates you from the competition and why clients should choose your business. Skip generic promises such as “excellent customer service” or “seasoned professionals” because most other companies already do that.
You should rather focus on specific advantages that customers actually need. For instance, offering 24/7 emergency response, transparent pricing, known insurance coverage, or specialization in mold removal projects will trigger specific audience pain points and help your business stand out.
You also need to outline your business goals here, both short- and long-term. Don’t try to sound over-ambitious. Focus on keeping your goals SMART: Specific, Measurable, Achievable, Realistic, and Time-bound.
Section 3: Market Analysis (Your Competitive Landscape)
For a restoration company, market analysis isn’t limited to collecting data from the competitors. It’s more about reducing risk for the investor than anything else. So, if you’re seeking investment, you need to focus on minimizing the risk factors.
That being said, investors don’t expect you to remove your competition entirely. They want to know if you have a solid understanding of what you’re up against. Your market analysis should indicate that you’re entering the market with realistic expectations rather than blind hope and assumptions.
Your market analysis should answer these important questions:
- Who are your customers?
- How much competition does your business already have?
- How much demand exists in your service area? and
- Where does your business fit in the local market?
Even if you don’t need the funding, this section can still outline how your business can get ahead of the competition.
- Define Your Target Market
Start by establishing your target market. Identify the types of customers you plan to serve, such as homeowners, property managers, or insurance companies. You can also target multiple groups at once.
Next, add key information about your target audience. Basic demographics are fine, but behavioral characteristics are much more important. Note the attributes that influence their buying decisions (i.e., lives beside a flood-prone river, building age is over 50, manages multiple commercial properties).
Lastly, explain your positioning: the reason you’ve chosen this specific market. Describe whether you’ve identified an underserved neighbourhood, have previous experience with the locals, see a specific restoration demand growing, or already have a referral ecosystem.
- Measure Your Local Competition
You’ll also need to measure how saturated your target market is against the demand. There is already growing demand on a national level.
According to the Insurance Information Institute (III), 1 in 60 insured houses file water/freezing damage claims each year. That number is even greater for wind/hail damage.
Here’s a good way to identify your local demand: multiply the number of households in your service area by that 1-in-60 claim frequency. This’ll show you the average annual claim in your area. It won’t be perfect or pretty, but it’ll highlight that you have a defensible estimate you can focus on.
Also, mention the frequency of local disasters, especially if you’re planning to offer emergency services.
Next, you’ll need to analyze your local competition. List the restoration companies within your service area that are already ranking on the Local Map Pack. List their services, coverage areas, specialties, and the community they serve.
Don’t keep your research limited to their website; look beyond. Go through their reviews, check how they position themselves in the market, evaluate their Google Business Profile, and cross-check their credentials. This’ll help you identify your competitive edge.
- Highlight Your Competitive Edge
Next, you’ll need to explain the way your business will keep up with the competition. Focus on the areas you think you can establish an advantage. For instance, you can focus on faster response, specialized expertise, smoother customer service, or better documentation.
Rather than claiming that you’re better than every competitor, or that there is no solid competition, try to identify a few realistic ways you can earn market share. The goal is to prove that there is room for another well-managed restoration company.
On a similar note, don’t forget to support your claims with reliable data whenever possible. This will do you a huge favor: replacing your assumptions with solid evidence.
You can also include data on your local population, housing stock, major insurance carriers, or weather patterns – everything that can influence the purchase behavior of your target audience. Industry reports, reliable statistics, and local market data will help strengthen your business plan.
Section 4: Organization & Management (Your Organizational Structure)
This section will outline the organizational structure of your restoration business, key roles, responsibilities, experiences, qualifications, and management hierarchy.
In other words, you’ll need to explain who owns the business, who will run the day-to-day operations, whether they are qualified enough, and how the company is structured. This is your chance to demonstrate that your company has the leadership and organizational structure required to operate and grow sustainably.
You’ve already mentioned your business structure in the legal entity part. Here, you’ll need to back that up with proper credibility. If your business has multiple partners, list everyone along with their ownership percentage, key roles, responsibilities, and credentials.
Next comes your management team. You don’t need a large team from the start. Many restoration companies start with the owner managing multiple roles, and that’s okay. Clearly stating the roles and responsibilities you manage is enough.
Don’t forget to highlight the experience, certifications, or industry knowledge your team has. If you need additional support or plan to hire more people in the future, mention the positions too. That’ll indicate that you’ve thought this through.
One thing to mention: you don’t necessarily need a Harvard degree to start a restoration company. If you lack experience or credentials, don’t hide that. Rather, explain your plan to fill the knowledge gap, such as hiring experienced technicians, collaborating with industry mentors, or investing in professional training.
Section 5: Services and Pricing (Your Profit + The Value You’ll Deliver)
Your services and pricing section may look like a simple list of your offerings, but it carries a deeper, more meaningful outcome: how your customers will perceive your business.
- List Your Services
There are many variables here that can impact how you approach your services. For example, the pricing model matters more than the prices themselves. This section should answer whether:
- Your cash flow mainly depends on insurance-paid work, or retail jobs.
- You offer emergency restorations only, scheduled operations, or both.
- You focus on mitigation/prevention services, or complete restoration programs.
- You prioritize high profit margin, or high volume.
Start by defining every restoration service you plan to offer. Shortly explain what each of them includes and why you think there’s a demand for them in your local market.
Additionally, if you plan to offer more specialized services (like moisture inspections, direct insurance billing, emergency board-up) down the line, you should also mention them since they’ll add to your revenue stream.
- Explain Your Pricing Policy
Next comes the most important part: pricing your services. There is no set-in-stone rule that you need to follow. However, if you choose insurance-funded jobs, they usually follow estimating platforms (like Xactimate, Symbility, or magicplan) and defined pricing guidelines.
On the other hand, if you prefer retail customers, you’ll need to write estimates based on labor, equipment usage, time, materials needs, and the scope of work.
Don’t forget about the TPA programs. Third-party Administrators (TPAs) will automatically send insurance claims to your business if you’re inside their network, but they’ll dictate the pricing. TPA jobs may look like free volume, but they’ll squeeze your profit margin.
If you want to protect your overall profit margin, we suggest limiting your TPA work to a small fraction of your revenue (ideally, below 5-10%).
Your business plan should briefly explain which pricing strategy fits your business model, and how you plan to keep your prices competitive without sacrificing your profitability.
- Mention The Value You’ll Deliver
Here’s another opportunity to help your restoration business stand out: explain the value you’ll deliver to your customers. Restoration services also include minimizing damages, helping people recover from disasters, or reducing downtime.
Namely, fast response time, quality workmanship, clear communication, reliable project management, or certified technicians – all of these will help your customers receive value beyond your physical restoration services.
This convenience and value becomes your Unique Value Proposition (UVP): the reason customers will choose your restoration agency over the competition. It has the biggest impact on your customers’ purchase behaviors and will help the reader clearly understand your competitive edge.
Lastly, don’t forget to mention your plan to review and adjust your pricing over time. No pricing strategy stays static as material costs change, labor expenses rise, or equipment maintenance becomes complicated. So, if you want to futureproof your business, you need to plan thoroughly.
Section 6: Marketing & Sales Strategy (How You’ll Reach & Convert Your Leads)
Even if your restoration business employs the best technicians in your state, buys the most advanced equipment, and provides the best quality services, you’ll still struggle to grow if you don’t optimize your marketing and sales strategy.
Buying equipment is usually the easy part. Building a business that keeps those machines working profitably is the bigger challenge.
So, instead of just writing “We’ll use social media and word of mouth”, you’ll need to plan a detailed roadmap that explores every key point of your customer journey. That includes how you collect leads and how you nurture, convert, and retain them.
- List the Channels You Collect Restoration Leads From
Start your plan at the first step of your customer journey: Acquisition. Identify and list all the channels you get restoration leads from. Also, group those channels by cost, and which one you own.
Your lead generation strategy will depend on your target market, and may include channels like:
- Local SEO (GBP)
- Paid Campaigns (PPC or LSA)
- Lead Collected from Your Website
- The Call/Quote Requests You Receive Over the Phone
- Referral from Plumbers, HVAC Contractors, or Property Managers
- Collaboration with Roofing/Insurance Companies
- Previous Customers or Their Referrals
- Paid/Free Lead Providers
In our opinion, the best lead sources are restoration SEO (local/organic growth), professional referrals (the warmest leads), and your past customers (long-term relationships).
Also, never depend on a single channel. Focus on building an automated lead generation pipeline that consistently delivers restoration jobs. The more diversified your lead sources are, the better.
State your marketing strategy for at least the first year. This includes the timeline, the channel, and your reason for choosing the channel, or the outcome you expect.
Your marketing to-do list will look something like this:
Months 1-3: LSA + Plumber Outreach (Immediate Jobs) + GBP/Review System Development
Months 4-6: PPC + Local SEO Foundation (Targeting Local Map Pack) + Email List Development
Months 7-9: Retargeting ads + Company Outreach + Seasonal Events (Community Build up)
Months 10-12: Industry Collaboration + SEO scaling + Conversion Optimization (Authority Building)
Also, don’t forget the acquisition math. PPC campaigns cost $10-$12 for each click, and purchased leads cost anywhere between $50 and $700+ (national average is $542).
On the contrary, Local SEO, your website, and leads from your previous customers will cost you more in time and effort than in money. When your website gets a lot of traffic but no leads, you’ll need a good conversion optimization (CRO) strategy rather than pouring more money into marketing.
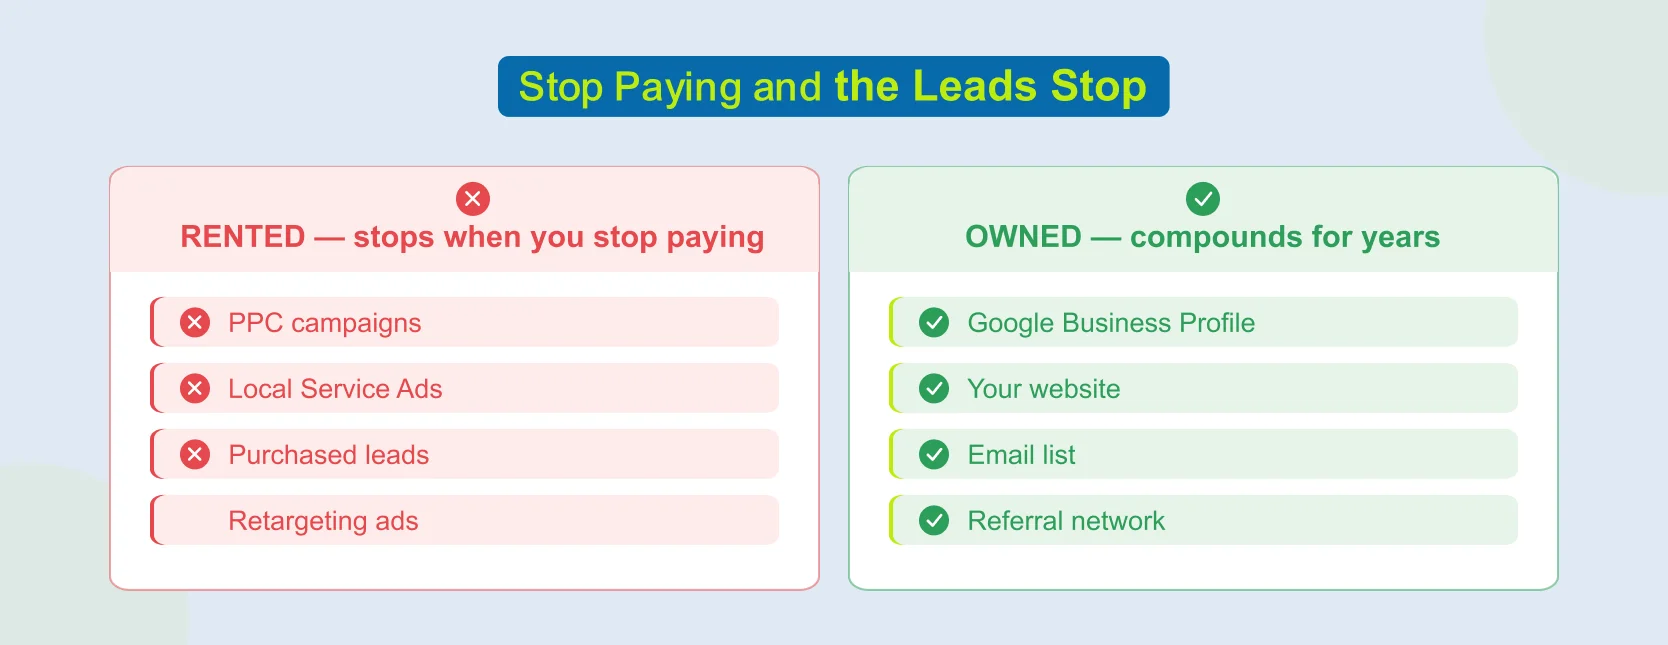
By now, you’ll have an important decision to make: whether to depend primarily on rented assets for your leads, or to build your own.
Rented Vs Owned Channels
Rented channels are those where you can buy immediate restoration jobs, but the leads stop coming as soon as you stop paying. For instance, you can get high-intent leads from PPC or LSA campaigns as long as you keep pouring money in.
On the flip side, you own channels like your GBP, website, email list, and referral network. The main cost here is your time and effort maintaining these channels.
What’s more, these channels compound over time. Once you develop them, you’ll keep getting leads for years to come.
- Explain How You Plan to Nurture Your Leads
Once your marketing channels start bringing leads, your sales channels start working and nurturing those leads. If your nurturing strategy is weak, it won’t matter how many leads you collect or how much quality the leads have.
Since you’ll be handing two different types of restoration leads (B2C leads from homeowners, and B2B leads from your referral network), you need to have a solid nurturing strategy for each.
So, you’ll need to describe how you are going to nurture and convert those leads. For the B2C leads, this includes handling incoming calls, scheduling inspections, drafting estimates, and following up consistently with the right message.
You’ll need a different approach for the B2B leads. A solid partnership program, regular physical meetups, and a specialized feedback loop will help you mature these leads effectively.
Also, include the channels you’ll use to mature those leads. Whether it’s automated email marketing, paid retargeting campaigns, two-way text sequences, or dedicated content marketing, mention how you plan to keep your leads engaged throughout their customer journey.
- Describe Your Plan to Build Long-term Relationships
Next, you can share your retention plan. Unlike in many other industries, retention takes a slightly different approach in the restoration industry. Here, a job well done doesn’t guarantee the customer coming back anytime soon.
What you can get instead is a valuable referral to their family, friends, colleagues, or neighbors.
That’s why your retention plan should primarily focus on B2B partnerships. We’re not saying that you drop your B2C clients from your radar altogether. They can still leave positive feedback which you can use to attract more leads.
So, plan for both. For the B2C leads, focus on low-frequency authority build-up: seasonal check-ins, helpful tips, and high-value educational content will do the trick.
For your B2B leads, develop an in-depth strategy containing an Emergency Ready Program (ERP), a two-way lead transfer strategy, and a specialized partnership plan.
- Mention The KPIs
Lastly, you’ll need to include the Key Performance Indicators (KPIs) you’ll use to measure your success and growth over time.
Besides giving you a bird’s-eye POV over your business, mentioning KPIs in your business plan will prove that you know how to manage a restoration company in a highly unpredictable and event-driven market.
The KPIs you track will depend on your specific business and growth goals. Here are some of the most commonly used KPIs you can consider:
Section 7: Operations/Implementation Strategy (How You’ll Achieve Your Goals)
To put it simply, your operation/implementation strategy will describe how you’ll manage your day-to-day operations, covering your crew, equipment, process, and systems you’ll need to rely on.
This section is here to prove that what you included in your business goals isn’t just fake promises; you have a solid strategy to achieve each of them.
- Explain Your Standard Workflow
Describe how your business will operate, starting from the moment a customer contacts you. Note down how you’ll schedule an inspection, draft an estimate, dispatch your crew, complete the restoration, and follow up after the job.
Your goal here will be to optimize your response time as much as possible. Because restoration jobs often depend on emergency responses, it can be the differentiator that compels a customer to choose your business over your competitors.
Not only that, but it also shows the reader that you not only plan to acquire new customers, but also plan to serve as many of them efficiently as possible.
In other words, response time is much more than just an operational metric. It’s part of the product customers are choosing today as well as the strategy that you’ll need to scale your business tomorrow without overwhelming your team.
- Share Your Staffing Plan
Outline the people you’ll need to manage your day-to-day operations as your business grows. As a sole owner, you may be wearing multiple hats today, but your business won’t grow this way.
So, plan ahead and list all the key roles your business needs now and will need later, including the estimated time when you’ll need them.
The structure will depend on your business model and goals, but some of the common roles include project managers, restoration technicians, office admins, estimators, customer service representatives (CSRs), business development executives (BDEs), or sales personnel.
Keep your plan realistic. Rather than showcasing explosive growth, your plan should reflect the growth rate you projected earlier. “We’ll double our workforce by next month” sounds impressive on paper, but it’s much harder to accomplish in real life.
- List the Equipment You’ll Need
Next, list the resources you’ll need to support those operations. This includes your facility, restoration gears/equipment, processes, documentation, and professional training for your crew.
If you’re starting a new business, honestly share your equipment capacity and your plan to expand over time.
Instead of spending a huge amount upfront to buy specialized gear, a better approach can be owning essential extraction/drying gear first and renting the specialty gear until your job volume increases.
Don’t forget about how you want to upskill your crew as your business expands. Share your training plan including all the certifications your crew will need (as per the IICRC standards), safety/quality control protocols, and how you plan to log everything neatly.
In the restoration business, delivering fast services alone isn’t enough. You’ll also need to be consistently reliable, and that means expanding your arsenal with the right gear, training, and process as your business grows.
Remember, lenders and investors generally prefer realistic growth plans over ambitious projections that need significant upfront spending.
- Describe Your Technology Stack
Also, include the technology you’ll need to grow your business, including a CRM, email marketing platform, project management software, booking/scheduling tools, GPC trackers, answering machines (to answer calls at 2 AM), cloud storage, or estimating platforms.
Because modern restoration companies need a lot more than just specialized equipment and expert technicians. You’ll also need to communicate with your clients/partners, keep your projects organized, document everything, and monitor your business performance.
Don’t just list every technology you plan to use. Explain how each tech can help improve efficiency, minimize workload, track progress, or deliver a reliable customer experience.
Growing your business is your ultimate goal, yes. But that doesn’t mean you have to sacrifice your service quality or operational efficiency.
- Mention Your Growth Milestones
Finally, mention the milestones you’ll use to measure your business growth over time. Break your long-term objectives into smaller milestones. That’ll give you clear benchmarks to aim for, making your business plan much more actionable.
For instance, share when you plan to launch your business, reach a set number of monthly completed jobs, purchase specialized tools, offer a new service, launch your app, expand your team with expert technicians, or open a new branch.
There is no hard and fast rule about setting milestones. But it’s better to tie your milestones to your assets and capacities rather than only time.
For instance, “Extending our fleet to 5 extraction trucks to unlock a $1M regional operational capacity by month 18” is much better than just saying “reaching $1M in revenue by month 18”.
Section 8: Financial Plan (The Break-Even Math and Projections)
This is the section most investors and lenders will check thoroughly, mainly because this section will translate all your ideas into numbers they can understand. It’ll also tie all the previous sections together to portray a clear picture about the fuel that runs your entire business engine: your finances.
So, double-check everything you put here, especially if you’re seeking financial aid. You’ll need to carefully calculate both your opportunities and risks to make your plan more realistic and convincing.
Show estimates on how much money you’ll need to start your restoration company, how much you expect to earn, what your ongoing expenses will be, and when you expect the business to become profitable.
- Calculate the Startup Cost
First comes the startup cost: the money you’ll need upfront to start your restoration company. This’ll consume a significant chunk of your total finances. The cost will depend on your niche, business model, location, service scope, equipment, and your initial team size.
The best practice is to group all your expenses into clear operational categories. Be as specific as possible and get real quotes for your market/niche; don’t just copy-paste a random template.
Most business plans contain an itemized breakdown in a table along with an explanation of the funding strategy. For instance, an itemized table for a single-truck startup operation may look something like this:
- State Your Monthly Operational Cost
Once you’ve calculated your startup costs, you’ll need to estimate how much money you’ll need per month to keep the business running. This is your minimum expense regardless of how many jobs you complete.
List your fixed expenses such as office rent, payroll, subscriptions, loan payments, utility bills, and insurance premiums. Variable expenses include fuel costs, equipment maintenance, subcontractor fees, material costs, and marketing budget.
Also, don’t forget other recurring expenses like repair costs or certification renewal fees. These are easy to overlook on their own, but pack them together, and they can eat a significant portion of your profitability over time.
Organize your monthly expenses into groups just like you did with your startup costs. This’ll make your job easier when you move on to calculating your break-even point.
Here’s a sample monthly operational cost-breakdown:
Note: Don’t copy-paste these figures. Use this table as a starting point and replace each estimate with your own.
Once you’ve listed all of your expenses, you’ll get a rough estimation of how much revenue your business needs to generate each month to stay afloat. This is the baseline of your day-to-day operations and all of your financial projections.
- Add Your Financial Projections
Next, you’ll need to add your financial projections: how you expect your restoration company to perform in the next 3-5 years.
Don’t overestimate. The numbers you mention here won’t match real-life results. It’s just a numerical version of the assumptions you’ve made so far.
The more important thing is to prove that what you’ve built is a logical financial model and it is supported by realistic assumptions rather than overinflated numbers. So, use the baseline plan you’ve already laid out in the previous sections.
If nothing else, your restoration company business plan should include a few key financial statements:
- Income Statement (Profit & Loss Statement): A datasheet containing your projected revenue, expenses, and net profit over a set period of time.
- Balance Sheet: A snapshot of the assets, liabilities, and equities of your business. This gives the reader a clear picture of your business’s current financial position.
- Cash Flow Statement: A datasheet estimating when and how much cash will enter and leave your business. It works as a time-lapse indicating when you’ll have enough money to cover your expenses.
Additionally, explain the assumptions behind your projections. Every number in your financial projections should be traceable to an earlier decision in your business plan. If you mention getting 15 leads per month in your previous sections, don’t show 25 in the projection.
Numbers without context are difficult to evaluate, and they don’t do anything except confuse the reader. So, each number in your financial projection should have enough traceable context.
- Highlight the Break-Even Math
Now comes one of the most important calculations of your entire business plan: The break-even math. In simple words, it indicates the amount of revenue your restoration company needs to generate or the number of jobs you need to complete before you start making a profit.
At your break-even point, the revenue you are generating is paying for all of your operating costs: both fixed and variable. Every job you complete before reaching that point helps your business survive, whereas every profitable job after that point helps it grow.
In this section, you’ll need to answer these critical questions:
- How many restoration jobs do I need each month to cover my expenses?
- What’s the minimum monthly revenue my business needs to stay afloat?
- How long might it take before the business becomes profitable?
The exact calculation depends on your pricing structure and operating costs. But here’s the basic formula:
Break-Even Point (BEP) = Fixed Costs ÷ Contribution Margin Ratio
Where Contribution Margin Ratio = (Price per Unit − Variable Cost per Unit) ÷ Price per Unit
- Mention The Cash Flow Reality Check
End this section with a reality check: the cash flow in the restoration business is different from most other service businesses.
The reason? Restoration work heavily depends on insurance jobs that typically involve delayed payments (usually 60 to 90 days). Although payments from retail jobs are faster to collect, they are usually harder to get consistently. As a result, projected revenue doesn’t mean the same as available cash.
So, your plan must include a working-capital cushion for that gap, and you need to state that explicitly.
A small reminder: a strong financial plan doesn’t need to predict the future with 100% accuracy. Nobody can do that. The goal here is to help the investor/lender realize that you understand the business landscape clearly.
Section 9: The Funding Ask (What Lenders Actually Check)
If you’re seeking funds for your business, use this section to explain how much funding you need, how you plan to use it, and what your repayment strategy is.
Don’t forget, investors/lenders are more interested in why you chose the number than the number itself.
Start by clearly stating how much funding you’re looking for, and then break down that amount into different ways you’ll use the money. Be as specific as possible.
For instance,
“We plan to raise $120,000 for the business. Here are the ways the money will be distributed:
- $60,000 on additional equipment and a vehicle to take on multiple jobs
- $25,000 to launch marketing campaigns and gain immediate leads
- $35,000 as working capital reserve for 3 months”
This breakdown feels way more reliable than just stating “we need $120,000 for growing our company”.
And if you’re not raising money, replace this section with your own investment plan: how much you’re putting in and what milestones to cross before you justify the next spend.
Section 10: Risk Management (How You’ll Put Out Fires)
No business is without risks. Anything from seasonal fluctuations to a slow economy can impact your business growth. Mentioning the risks and developing contingency plans will showcase that you’re prepared to deal with any challenges that may come your way.
Start this section by listing all the potential risks your business might face. These include:
- Seasonal Demand Fluctuation
- Delay in Insurance Payments
- Rising Labor & Equipment Costs
- Vehicle or tool Breakdown
- Lead Source Disruption
- New Competitor Arrival
- Catastrophic Events
- Technician Shortage
- Legal Disputes
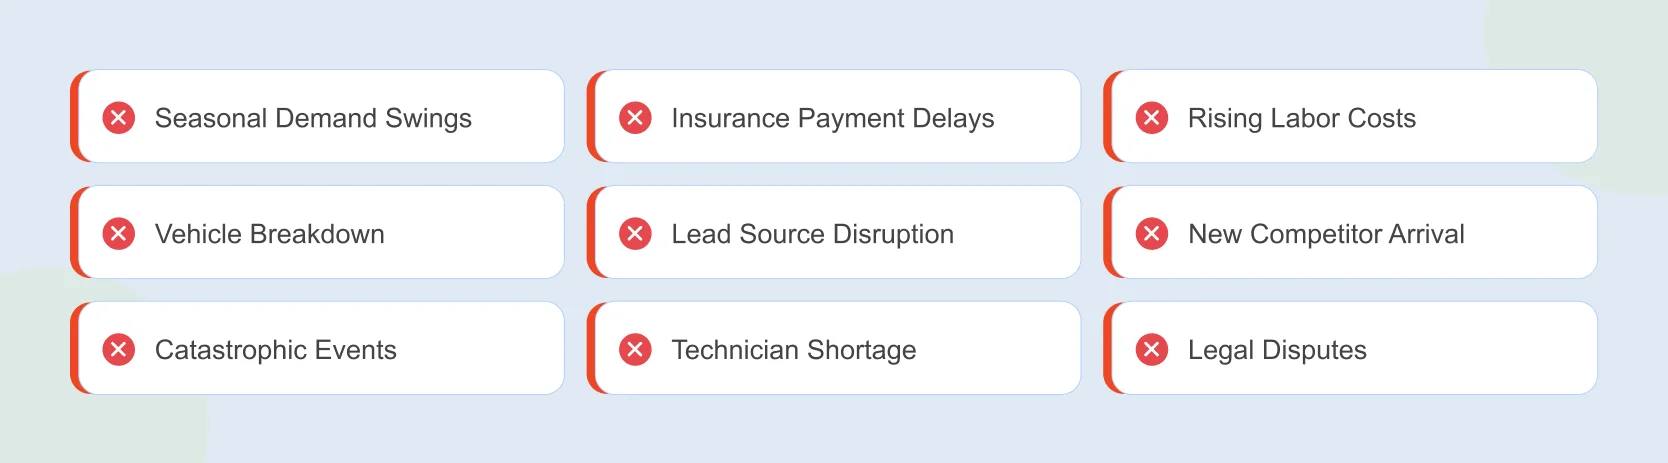
Next, develop a contingency plan for each. Prevention is always better than mitigation. Group them into two segments: risks that you can control and external risks. Protect your restoration business from internal issues and prepare it for the rainy days.
Also, explain how you’ll review and update your business plan over time. External factors like changing markets and evolving customer expectations can hit your business at any time. Even your business priorities may shift.
Revisiting your business plan on a regular basis will help your business respond to those new challenges before they become larger issues.
The Mistake That Kills Most Business Plans
The number one killer of a restoration company business plan is to write one only to impress the investor and then forget about it. The main purpose of this plan is to guide your business as opposed to securing a loan and then never touching it again.
We’ve seen many business plans filled with ambitious revenue goals, heavyweight management panels, aggressive marketing/expansion strategies, and over-optimistic financial projections. All of them looked impressive on paper, but very few of them could realistically deliver on the promises they made.
Your business plan shouldn’t focus on the best-case scenarios only. It should reflect what you can launch, operate, and grow using the resources you have today. If you build a plan only to awe the investors, it’s bound to end up rotting somewhere in your drawer.
The good news is: avoiding this issue is simpler than you think.
Use your business plan as a decision-making tool and keep revisiting it periodically. Allocate an hour each quarter to evaluate the targets you’ve hit and the ones that you’ve missed. Once a year, go through each section and update it according to your new business goals.
It’s that simple. It might look boring, but if you do this, the result will genuinely shock you.
Conclusion: Build the Business, Not Just the Plan
If you haven’t realized, you’ve already done most of the homework needed to establish and grow a restoration company from scratch. The business plan you’ve built so far is also a practical guide for making better decisions as your company grows.
Every section of your business plan will force you to think through an important part of the business in real life. Those decisions create a stronger foundation than relying on expensive trial and error after your business is already running.
To keep it functioning in the long run, revisit the plan regularly, update your assumptions, and adjust your strategy to match new opportunities and challenges.
Would you like a second opinion on your business plan?
Feel free to reach out. Our seasoned team has helped restoration companies turn their business plan into a growth strategy. If you want more context, we’ve helped a few restoration companies overcome serious obstacles including updating their business strategy, recover web traffic, reach new markets, and build strong online presences.
With dedicated services like organic/local SEO, email marketing guidance, lead generation strategies, and conversion optimization, we’re here to help you build a business that’s resilient and profitable.
FAQs
Md Tanvir Ahmmed
Local SEO Strategist, Restoration SEO Specialist
Get Quality Leads from Us
PexNet Newsletter - Subscribe for SEO news, trends, updates, & more.
Share This Post




 100% Free
